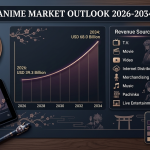

According to IMARC Group, the global anime market was valued at USD 36.1 Billion in 2025 and is projected to reach USD 68.0 Billion by 2034, expanding at a CAGR of 7.08% during 2026–2034. These figures reflect surging global demand, the rise of streaming as the primary distribution channel, and an increasingly diverse anime market share across geographies.
Anime Industry Overview
Anime Japan's distinctive style of animated storytelling — has evolved from a domestic broadcast medium into a global multimedia ecosystem. The industry today spans television series, theatrical films, direct-to-video releases, internet streaming, merchandising, music, pachinko gaming machines, and live entertainment events. This diversity of revenue streams is a defining characteristic of the anime market size and a key reason for its resilience against broader media headwinds.
Major studios such as Studio Ghibli, Kyoto Animation, Toei Animation, and Bones have built internationally recognized brands, while streaming platforms like Crunchyroll and Netflix have dramatically accelerated global distribution. The result is an industry where a series premiering in Japan can simultaneously reach audiences in São Paulo, Paris, and Lagos — often within hours.
Key insight: The anime industry's unique model — where a single IP can monetize across broadcast, streaming, merchandise, gaming, and live events — creates compounding revenue that few entertainment sectors can match.
Request for a Sample Report for Detailed Anime Market Share Evaluation: https://www.imarcgroup.com/anime-market/requestsample
Global Market Overview & Anime Market Statistics
Below are the key anime market trends and statistics drawn from IMARC Group's comprehensive market analysis:
|
Report Attribute |
Key Statistics |
|
Base Year |
2025 |
|
Historical Period |
2020–2025 |
|
Forecast Period |
2026–2034 |
|
Market Size in 2025 |
USD 36.1 Billion |
|
Market Forecast in 2034 |
USD 68.0 Billion |
|
Market Growth Rate (2026–2034) |
7.08% CAGR |
|
Largest Region |
Asia Pacific (38.7% share, 2025) |
|
Largest Segment by Revenue |
Merchandising (35.8% share, 2025) |
The anime market share data underscores how the industry has matured: from a Japan-centric export into a truly multi-polar global market. North America — led by the United States at 80% of the region's contribution — has become a critical growth engine, while Asia Pacific retains its foundational dominance due to production volume and cultural proximity.
Key Market Drivers & Trends in 2025
Several powerful forces are converging to sustain the anime market trends and fuel continued double-digit growth in valuations through the next decade:
Streaming Platform Expansion
Platforms such as Crunchyroll, Netflix, Disney+, and Amazon Prime Video have made simulcast releases the norm, exposing global audiences to new titles the same day they air in Japan. The EU's 94% household internet penetration rate in 2024 exemplifies the addressable market for digital distribution.
Franchise IP Longevity
Established franchises like Dragon Ball Daima and One Piece continue generating new seasons, theatrical releases, and branded experiences. Each new installment reinvigorates merchandise sales and recruits younger viewers, sustaining long-term anime market value.
CGI & Digital Production Tools
Advanced CGI integration and cloud-based production pipelines are improving visual quality while reducing turnaround times. With approximately 50% of animation studios expected to be cloud-based by 2026, production capacity is set to expand significantly.
Cross-Media Adaptations
Anime IPs are increasingly spawning video games, live-action films, stage productions, and theme restaurant experiences — such as the One Piece-themed restaurant that opened in Las Vegas in May 2024 — creating layered revenue beyond traditional broadcast and streaming.
Convention & Fan Economy Growth
Events like Anime Expo, Otakon, and international equivalents drive merchandise sales, cosplay culture, and community loyalty. These gatherings reinforce the anime market share of premium and limited-edition product lines.
International Co-Productions
Studio partnerships between Japanese producers and Western distributors are increasing output and funding pools. LDH Japan's January 2025 launch of the LDH Animation brand signals growing appetite for original international production and licensing deals.
Key Market Segmentation
Understanding the anime market size requires analyzing how revenue is distributed across distinct categories. The industry's segmentation reflects the many ways fans engage with and spend on anime content:
By Revenue Source
All Segments
Merchandising — Largest (35.8%)
TV Broadcast
Movie
Video
Internet
Distribution
Music
Pachinko
Live Entertainment
Merchandising leads the market with a 35.8% share in 2025, driven by global demand for apparel, action figures, posters, and home décor. The rise of e-commerce and limited-edition brand collaborations — such as Toei Animation's streetwear partnership with HYPLAND for One Piece — has supercharged this segment far beyond traditional retail.
Internet distribution is the fastest-evolving segment, as streaming platforms invest heavily in exclusive licensing and original anime productions. This shift is a primary driver of the expanding global anime market value, as platform revenues supplement and increasingly rival traditional broadcast income.
Regional Market Analysis
The anime market trends vary considerably by region, reflecting differences in cultural affinity, infrastructure, and monetization maturity. Here is how the global landscape breaks down:
Asia Pacific
Largest — 38.7%
Japan remains the production heartland, backed by government cultural export programs. China, South Korea, India, and Indonesia are high-growth consumption markets, benefiting from surging mobile data usage (India averaged 20.27 GB/user/month by March 2024) and digital streaming investment.
North America
The United States dominates at 80% of regional share, fueled by 246 million social media users (January 2023) and a mature streaming infrastructure. Platform exclusives, dubbed content, and major conventions such as Anime Expo drive high per-capita spending on anime market merchandise and subscriptions.
Europe
Germany, France, the UK, Italy, and Spain benefit from expansive multilingual streaming libraries. Events such as Japan Expo in Paris and MCM Comic Con in London anchor a passionate and growing collector and cosplay community. EU household internet access at 94% in 2024 enables broad streaming reach.
Latin America
Brazil leads the region with 210.3 million active mobile connections in early 2024. Nostalgia for Dragon Ball Z and similar generational series drives strong brand loyalty, while platform growth and mobile adoption are rapidly converting casual viewers into paying subscribers.
Middle East & Africa
A young population — the Arab region's 15–24 cohort numbered approximately 82 million in 2023, projected to reach 108 million by 2050 — combined with streaming growth and localized content investment, is establishing the region as a key growth frontier for the anime market share.
Connect for Detailed Anime Market Share Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=6992&flag=C
Leading Players in the Anime Industry
The global anime market features a mix of storied Japanese studios, global streaming platforms, and specialized distributors. The following companies are covered in the IMARC Group competitive analysis, which includes market structure mapping, player positioning, top winning strategies, and a company evaluation quadrant:
- Aniplex of America Inc.
- Bones Inc.
- Crunchyroll
- Kyoto Animation Co. Ltd.
- Madhouse Inc.
- P.A. Works Inc.
- Pierrot Co. Ltd.
- Shout! Factory LLC
- Studio Ghibli Inc.
- Toei Animation Co. Ltd.
- VIZ Media LLC
Competition in the anime market is intensifying as streaming platforms move beyond licensing into original production, and as traditional studios forge new international partnerships to co-fund and co-distribute content. Brand collaborations — streetwear, food and beverage, gaming — are becoming a significant competitive differentiator.
Latest Industry Developments
Jan 2025
LDH Japan — LDH Animation Launch
LDH Japan launched the LDH Animation brand, entering original anime production and international licensing, signaling growing confidence in cross-border content investment and expanding the anime market value pipeline.
Dec 2024
Toei Animation × HYPLAND — One Piece Streetwear
Toei Animation and HYPLAND announced their second One Piece streetwear collaboration, reinforcing how franchise IPs are driving premium merchandise revenues and deepening the fashion crossover segment.
Dec 2024
Iyuno — Medalist
English DubIyuno cast lead performers for the English dub of Medalist, which premiered on Hulu on January 4, 2025 — illustrating the acceleration of English-language localization pipelines that boost anime market share in Western markets.
May 2024
One Piece Las Vegas Restaurant
A One Piece-themed dining experience opened in Las Vegas, marking a milestone in live entertainment monetization of anime IPs beyond convention floors and retail shelves.
May 2024
Rakuten Group — Rakuten Panda
Rakuten Group announced its first original anime series, Rakuten Panda, scheduled for fall 2024 — demonstrating how technology and e-commerce conglomerates are entering the production market to leverage anime market trends.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Retail, Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104