

Dry Type Transformer Market to Reach USD 13.21 Billion by 2034 as Grid Modernization and Industrial Electrification Accelerate
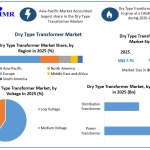
The Dry Type Transformer Market is entering a sustained growth phase as utilities, industrial facilities, commercial buildings, data centers, and renewable energy projects increasingly require safe, efficient, and environmentally responsible power-distribution equipment. According to Maximize Market Research, the global Dry Type Transformer Market was valued at USD 7.75 billion in 2025 and is projected to grow at a CAGR of 6.1% from 2026 to 2034, reaching nearly USD 13.21 billion by 2034.
Market Estimation, Growth Drivers and Opportunities
Dry type transformers are gaining importance because they do not use insulating liquids and therefore reduce risks associated with oil leakage, fire, and environmental contamination. Their suitability for indoor installations, urban substations, commercial complexes, industrial plants, renewable energy facilities, and infrastructure projects is strengthening demand.
A major growth driver is the modernization of electricity transmission and distribution infrastructure. Aging grids require replacement and capacity upgrades, while expanding renewable power generation is creating new requirements for reliable voltage transformation and distribution. Industrialization and urbanization are also increasing electricity consumption, supporting deployment across manufacturing plants, commercial buildings, utilities, transportation infrastructure, and other high-load applications.
Cast-resin technology is another important opportunity. Encapsulating windings in epoxy resin provides protection against moisture and supports operation in challenging environments. Dry type transformers also offer high overload capability, low partial discharge, low losses, fire resistance, and relatively low maintenance requirements.
Opportunities are emerging from artificial-intelligence data centers, semiconductor manufacturing, electric-vehicle infrastructure, renewable generation, battery storage, and distributed energy systems. These applications require reliable electrical distribution in locations where safety, compact installation, and environmental performance are important.
Get a Sample Insight Report Now : https://www.maximizemarketresearch.com/request-sample/11250/
U.S. Market Trends and Investment
The United States became a major focal point for transformer manufacturing investment during 2025 as utilities, data centers, industrial facilities, and grid-modernization projects faced increasing transformer demand. Eaton announced a USD 340 million investment in a new South Carolina facility to increase U.S. three-phase transformer production, with production and hiring planned to begin in 2027. Hitachi Energy also announced major U.S. manufacturing investments, including expansion of dry-type transformer production in Virginia and a broader USD 1 billion U.S. grid-infrastructure investment program. Siemens Energy was simultaneously advancing its U.S. transformer manufacturing expansion, targeting domestic production of large power transformers from 2027. These investments reflect a wider shift toward localized electrical-equipment supply chains as data-center construction, electrification, renewable integration, and grid replacement increase transformer requirements.
Market Segmentation: Largest Segments
Based on the market segmentation framework used by Maximize Market Research, the Dry Type Transformer Market is divided by Voltage, Type, Phase, and Application.
Among voltage categories, Medium Voltage represents the leading market segment in broader industry estimates, supported by extensive deployment across industrial facilities, commercial infrastructure, renewable projects, and distribution networks. Recent market analysis places medium voltage at 47.2% of global dry type transformer revenue in 2025. By application, the Industrial segment accounted for the largest share in 2025 in broader industry estimates, reflecting demand from manufacturing plants, processing facilities, automated production environments, and heavy industrial installations.
Competitive Analysis
The competitive landscape includes major electrical-equipment manufacturers with extensive transformer portfolios, manufacturing networks, engineering capabilities, and investments in grid technologies.
Siemens AG: Siemens Energy announced a €220 million investment in its Nuremberg transformer facility in Germany in September 2025, expected to increase production capacity by approximately 50% and create 350 jobs. The expansion is designed to address rising global demand for transformers and strengthen manufacturing capacity.
Schneider Electric SE: Schneider Electric continued strengthening its global manufacturing and supply-chain footprint. In July 2025, the company agreed to acquire the remaining 35% stake in Schneider Electric India for €5.5 billion, supporting its strategy to make India a major regional R&D and supply-chain hub. Schneider also maintains a broad cast-resin dry-type transformer portfolio designed for reliability, safety, and long service life.
Eaton Corporation PLC: Eaton's 2025 USD 340 million South Carolina investment is directly connected to expanding transformer manufacturing capacity. Its dry-type portfolio includes medium-voltage, cast-coil, VPI, VPE, and RESIBLOC solutions, providing customers with fire-resistant and environmentally focused alternatives for industrial and commercial applications.
ABB Ltd: ABB continued developing digital and environmentally focused transformer technologies. In December 2025, ABB introduced BABA-compliant three-phase low-voltage dry-type transformers for the U.S. market, supporting federally funded infrastructure projects and emphasizing localized sourcing and manufacturing.
TBEA Co. Ltd: TBEA continues expanding its transformer capabilities around the development of renewable-energy-oriented power systems. Its transformer business supports equipment and integrated solutions spanning source-grid-load-storage applications, including transformers from 10 kV to 1000 kV and renewable-energy infrastructure services.
Regional Analysis
United States: The U.S. market is being supported by grid modernization, data-center construction, industrial reshoring, renewable-energy integration, and domestic manufacturing investments. Transformer shortages and long procurement cycles are encouraging manufacturers to expand local production.
Germany: Germany remains an important transformer manufacturing and engineering hub. Siemens Energy's €220 million 2025 Nuremberg expansion demonstrates continued investment in European transformer production and capacity.
China: China is a major contributor to Asia Pacific demand due to industrialization, expanding electricity infrastructure, renewable-energy deployment, and large-scale wind and solar development. The MMR analysis identifies Asia Pacific as the largest regional market, with China's renewable-energy expansion supporting continued demand for dry-type transformers.
Key Players
The major companies covered in the Dry Type Transformer Market include Siemens AG, Schneider Electric SE, Eaton Corporation PLC, ABB Ltd, TBEA Co. Ltd, Hyundai Electric & Energy Systems Co. Ltd, Hammond Power Solutions Inc., Kirloskar Electric Company Ltd, Hitachi Energy Ltd, Gujarat Transformers Private Limited, Fuji Electric, Toshiba, TRENCH, BHEL, and Voltamp.
Why This Market Matters Now
The Dry Type Transformer Market matters now because electricity systems are undergoing simultaneous modernization, electrification, decentralization, and digitalization. Data centers and AI infrastructure are increasing electricity demand, renewable projects are changing power-flow requirements, and aging grids require extensive replacement and expansion. Dry type transformers provide a combination of fire safety, reduced environmental risk, indoor installation flexibility, and low-maintenance operation that aligns with these evolving infrastructure requirements.
With the market projected to increase from USD 7.75 billion in 2025 to nearly USD 13.21 billion by 2034, manufacturers are expected to focus increasingly on production capacity, digital monitoring, advanced insulation materials, energy efficiency, compact designs, and localized supply chains.
Explore More Related Reports:
Data Visualization Market https://www.maximizemarketresearch.com/market-report/global-data-visualization-market/100013/
Global HVAC Sensors and Controllers Market https://www.maximizemarketresearch.com/market-report/global-hvac-sensors-and-controllers-market/49573/
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us
Maximize Market Research Pvt. Ltd.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: [email protected]